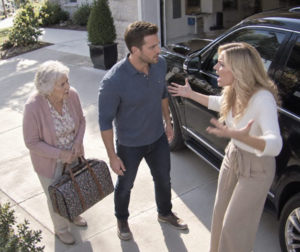
Mi madre estaba de pie en el vestíbulo con una bolsa de hospital pegada al pecho cuando Vanessa la miró y le dijo: “Tu madre no es mi responsabilidad”.
No hubo gritos antes. Ninguna pelea dramática. Mamá tenía programada una prueba cardíaca en el Hospital St. Catherine’s después de varias semanas de dificultad respiratoria cada vez mayor, y su médico quería que la ingresaran durante la noche porque una tomografía había mostrado un problema en una válvula que podría requerir cirugía. Su transporte se canceló a último minuto. Le pregunté a Vanessa si podía usar la camioneta porque mi sedán estaba en el concesionario. Miró a mamá, luego a mí, y dijo que necesitaba la camioneta a la mañana siguiente para el almuerzo con su hermana. Cuando le recordé que se trataba de una hospitalización, se cruzó de brazos. “Daniel, estoy harta de que cada problema de tu familia se convierta en nuestro problema”.
Mamá susurró inmediatamente: “Puedo llamar a otra persona”.
Eso dolió más que la sentencia de Vanessa.
Durante seis años, mamá no nos pidió casi nada. Tras la muerte de papá, vendió la casa familiar, se mudó a un pequeño apartamento y rechazó todas mis ofertas para pagar sus cuentas. Sin embargo, cuando Vanessa fundó su empresa de diseño de interiores tres años antes, mamá había invertido 120.000 dólares del seguro de vida de papá porque creía en ella. Vanessa la llamaba “la madre que nunca tuve” mientras se hacían efectivos los cheques.
Ahora mamá necesitaba que la llevaran.
Saqué mi abrigo del armario.
—¿Daniel? —dijo Vanessa.
Cogí la bolsa de mamá.
“Me compraré un coche.”
“¿En serio te vas por esto?”
La miré fijamente durante un largo rato.
“No. Me voy porque por fin te he oído con claridad.”
Fuimos al hospital en un servicio de transporte compartido.
A la 1:40 de la madrugada, mientras mamá dormía después de las pruebas, me senté en una silla de plástico fuera del departamento de cardiología y llamé a mi abogada, Rebecca Sloan. Vanessa y yo llevábamos casi un año con problemas. Habíamos tenido habitaciones separadas, discusiones por dinero y tres sesiones de terapia a las que Vanessa dejó de asistir porque decía que yo estaba “demasiado apegado a obligaciones que no eran nuestras”.
Rebecca ya tenía un borrador de acuerdo de separación.
Le dije que lo enviara.
Pero antes de que lo hiciera, le pedí que revisara un documento más: la garantía personal que había firmado para la empresa de diseño de Vanessa cuando se expandió con una segunda sala de exposiciones.
La garantía expiró a los noventa días.
Rebecca dijo: “No es necesario renovarlo”.
“Lo sé.”
A las 8:15 de la mañana siguiente, un mensajero entregó un sobre en nuestra casa.
Inside was the separation notice, revocation of Vanessa’s access to my business accounts, and formal notice that I would not renew my personal guarantee when her company’s $1.3 million credit facility came up for review.
Nothing was being canceled overnight.
Nothing was being seized.
Vanessa simply had ninety days to finance her own company without using my balance sheet.
My phone began vibrating at 8:31.
By 10:00, she had called thirty-eight times.
I ignored every one until Mom’s cardiologist finished speaking.
She needed valve surgery.
Then Rebecca called me.
“Daniel, there’s another issue.”
“What?”
“Vanessa’s lender sent over the guarantee file.”
I stood.
Rebecca continued.
“Someone submitted a renewal request three weeks ago.”
My stomach dropped.
“I never signed one.”
“I know.”
A pause.
“Daniel, the document says you did.”
Rebecca’s first instruction was to stay focused on Mom. A questionable guarantee could be preserved and investigated; my mother was preparing for major surgery. I gave Rebecca written authority to communicate with the lender and returned to cardiology.
The guarantee renewal was not yet effective. Vanessa’s company had requested an extension of its existing credit facility, and the bank was still reviewing the package. That mattered. No new debt had become mine simply because someone submitted paperwork carrying my name.
My supposed signature appeared on a consent page dated three weeks earlier. Rebecca compared it with an older guarantee I had genuinely signed two years before. The shape, spacing, and even a tiny break in the final letter looked almost identical.
The lender preserved its upload records. The renewal package had been submitted through an outside accountant who handled Vanessa’s company finances. He told the bank Vanessa had provided the signed document and said I was traveling.
Vanessa finally reached me through Rebecca. Her explanation was that the renewal was “routine” and she believed I had already agreed to continue supporting the company. I asked whether I had signed the page.
She avoided the question.
That afternoon, Mom woke after a procedure to stabilize her before surgery. She saw my face and immediately asked, “What did Vanessa do?” I told her only enough to explain why I was staying at a hotel instead of going home.
Mom became very quiet. Then she said something I did not expect: “Ask about my investment.”
Three years earlier, Mom’s $120,000 had been documented as convertible debt in Vanessa’s business—not a gift. Vanessa had made interest payments for six months, then told Mom the company needed temporary relief. Mom never mentioned it to me.
Rebecca obtained the records with Mom’s permission. The note had matured eight months earlier. No repayment had been made, and no conversion agreement had been signed. Vanessa’s company still owed Mom principal plus accrued interest.
I felt sick. The woman who had said my mother was “not her responsibility” had been using my mother’s money for years while quietly ignoring the repayment date.
Vanessa insisted cash flow had been tight and said Mom never demanded payment. That was true. It did not erase the obligation.
The lender’s forensic review produced the stronger evidence two days later. The disputed signature image had been embedded into the PDF from a scanned copy of my old guarantee. Metadata showed the file had been assembled on Vanessa’s office computer.